Sunday, January 26, 2020

Data Briefing: How 'Real' Are Retail Sales?

Merrily, we roll along.
Data released this morning support the sense that the U.S. economy remains buoyant.  We wonder though.
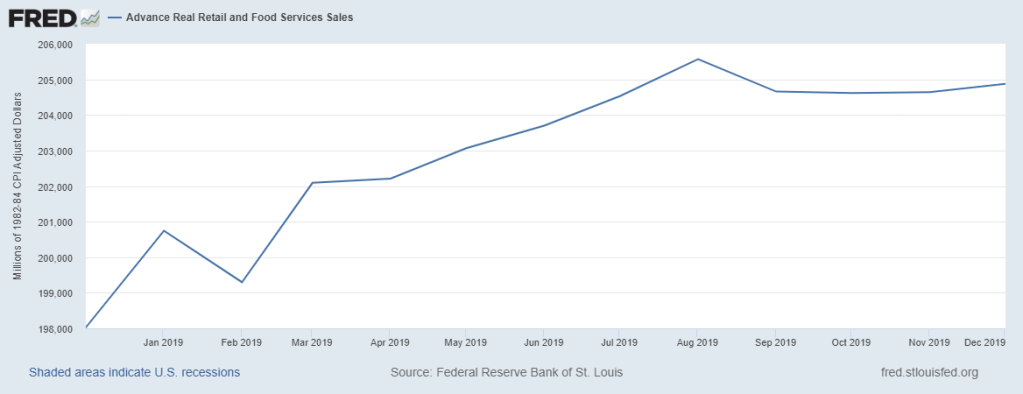
Let’s get to the headline: the U.S. Census Bureau reported that retail sales rose 0.3% in December and up 5.8% from December 2018. 
It is curious to us, though, that the headline figure from the Census Bureau is adjusted for seasonal variation but not inflation.  Using the consumer price index as a deflator, the St. Louis Fed figures show just a 0.1% increase in retail sales in December from the previous month and up just 3.5% year over year.
Some details from the retail sales data worthy of note:
  • Nonstore retailers (read on-line) garnered the highest sales figure of all categories excluding autos, posting $66.765 billion in seasonally adjusted sales, compared with $66.635 billion in November, an increase of about 2%.  For the year, nonstore retailers had sales of $778.374 billion, up 13.1%.
  • Department stores continued to lag, with seasonally adjusted sales of  $10.936 billion vs. $11.019 billion in November, down about 0.8%.  For the year, department stores saw a 5.5% decline in sales.
Meanwhile, the Department of Labor said initial claims for jobless benefits fell 10,000 to 204,000, the fifth straight week of declines and reinforcing the sense that if you want a job you can get one.

The Great Fires of 2020

First published at TalkMarkets.com Jan. 15, 2020
We know, gentle reader, you have been mystified and concerned that our voice had been stilled by the deep state or that Ukrainian interlopers had taken control of our server.  Fear not, friends.  We are in fine trim and back to prognosticating as the teens of the 21st century give way to what we hope (we’re always ready for a good time) will be the roaring ’20s.
Without the benefit of Big Data (we consider it cheating), here’s what’s coming up, in no particular order because all are of importance.
  • We “called” Donald John Trump’s election four years ago (see https://seekingalpha.com/article/3782936-happy-of-2016) but see all sorts of reasons why he should lose this time around.  Yet, as excruciatingly painful as it may be, we find it hard to believe a man — even an out-of-his-depth, Philistine man-child — enjoying the longest expansion in U.S. history with unemployment below 4% could possibly lose.  This depends, of course, on the likely outcome the president is not removed from office.  Despite what they say, Democrats must root for financial panic.
  • Infamously, we have been perma bears on the stock market and extollers of the virtues of bonds.  It wasn’t a horrible call.  We advised buying the 10-year note at a 3% yield, and debt has done nicely since.  But we whiffed on the stock market, which appreciated 25% or so in 2019, depending on your index of choice.  Calling a top is futile, but we note that total market capitalization over gross domestic product is well over 150%, a level that historically signals significant overvaluation.  Either it’s different this time (for instance, the idea that the supranational nature of enterprise requires a more global perspective than U.S. GDP), or equity returns are destined to be negative this year.  Sell bonds (see inflation discussion below). Pare equity positions, but own Amazon (AMZN), the only retailer we see benefiting from either higher or lower consumer prices.
  • Here’s a no-brainer: We’re doomed!  The most underreported story of 2019 was a continent on fire.  If charred koala corpses don’t do it, nothing will.  Climate change-fueled disasters will increase in frequency and intensity, but nothing will be done.  A wise confidante of ours says that any problem that calls for collective action will be opposed immediately by the Trumpist know-nothings who, like Huck Finn’s pap, blame “guvment” for any and all miseries.  Or, as another Huck Finn character, the Dauphin, says: H’aint we got all the fools in town on our side? And ain’t that a big enough majority in any town? Oh, the humanity!
  • The Federal Reserve System’s Open Market Committee won’t raise rates in 2020.  When they do, it’ll be too late.  It will only do so if bond market vigilantism comes back in vogue. We know monetarism is out of fashion, last employed by the late Paul Volcker to conquer inflation in the 1980s.  The linkage between money supply and inflation appears to be severed, but only because the velocity of money has been on a downward trend since the great recession and has kept sliding during this long recovery.  Data from the Federal Reserve Bank of St. Louis show the M2 money stock increasing about 85% in the decade ending Dec. 31, while velocity has decreased 25%.  This is puzzling, but suggests to us inflation could return if velocity returns to a more “normal” level and lazy people like us don’t boost our productivity growth.  In any event, the Fed won’t risk the political fallout of raising rates, especially in Trump’s re-election year, unless the consumer price index itself turns decisively higher. 
  • Unless we return to “a world lit only by fire” (William Manchester’s term for the middle ages), gold will become more of a barbaric relic, owned only by scolds who, like the puritans, are worried somebody, somewhere is having a good time.  Then again, the world may very well be on fire by the end of the decade.
  • Some bubble will burst in 2020.  We can’t tell you if it will be housing again or corporate debt or student debt, but the world is due for something to blow up.  Take the corporate sector.  According to MacroMavens’ Stephanie Pomboy, the top three companies in the S&P 500 have more cash than the bottom 450 combined, leaving one to wonder how the nearly $10 trillion in corporate debt can be serviced if the world gets wobbly.
  • On the sporting front, which, after all, is where the real money is, the rich get richer.  The New York Yankees with the signing of starting pitcher Gerrit Cole will be world champions this year, and the Dallas Cowboys, under new coach Mike McCarthy, will win the Super Bowl next year.  Matthew Wolff, the young golfer with the unorthodox baseball swing, will win two major tournaments this year.
Which reminds us that if we remember to keep our head down, turn not sway, and keep the left arm pinned to our chest, breaking 90 in the sporting life ahead is within our grasp.  If not, there’s always next year.  So we have that going for us.

Monday, December 31, 2018

Suffering with Sontag

(First published Dec. 26, 201, on TalkMarkets.com)
At the end of the year, we were thinking of Susan Sontag for some reason. We took “Against Interpretation and Other Essays” (1966) down from the shelf and turned to “The Artist as Exemplary Sufferer.” Speaking of ancient Hebrew, Greek, and Oriental literature, she wrote: “Suffering was not the hallmark of seriousness; rather, seriousness was measured by one’s ability to evade or transcend the penalty of suffering, by one’s ability to achieve tranquility and equilibrium.”
Replace “Artist” with “Equity Investor” and which might be the real exemplary sufferer is clear. Like Sontag’s ancients, we prefer to be serious about sidestepping the penalty of investing in what we believe to still be an overvalued stock market.
Back in March, we wrote in these pages:
“In any event, gentle reader, we think equities, even Facebook, are dead money or worse for a while. The likeliest bull market to come, despite Fed tightening, is bonds, we believe. We know that some heavy-hitting interest rate gurus believe bond prices are headed downward. But we think an inverted yield curve looms as the Fed squeezes and investors flee to safer assets. If the 10-year note yield hits 3% (it’s currently about 2.85%), it’s a screaming buy, we think.” (see What Rough Beast?).
And in June, we again expressed our preference for bonds over stocks (see Is Your Daddy Rich And Your Momma Good Lookin'?)
Alas, the bottom in equities has not yet been plumbed, in our view. Here’s why:
How much is that doggie in the window? Valuation has been excessive for some time and remains so despite the December sell-off. For reasons that only the gods know, this pendulum tends to swing way out of whack in both ways, perhaps because human beings expect either the best of all possible worlds or the end of time. In any event, at the end of the Christmas Eve bloodbath, the broad stock market was capitalized at about 123% of gross domestic product, still way too rich, in our view, given signs of a global slowdown, starkly evident in crude oil prices.
Ye olde yield curve. Inversion is in the eye of the beholder. The two-year to10-year spread was still positive at 19 basis points at the close of trade Dec. 24, according to U.S. Treasury data. That spread has narrowed from 58 basis points at the beginning of the year. However, the TIPs, or inflation-protected bonds, showed an inversion between the five-year and 10-year yields. We find this ominous in that it foresees a policy mistake of tightening too zealously by the Fed, the traditional trigger for economic downturns.
Donald Trump is in over his head. Forget the girls, Russia, emoluments, etc. No matter what echo chamber you frequent – be it “Fox & Friends” or “Morning Joe” – it is clear by now that President Trump could be non compos mentis with no strategy but the seat of his pants.
  • Though he hailed his meeting with China’s Xi Jinping earlier this month as a deal of some sorts, what exactly was struck other than a delay in tariff impositions remains ambiguous.
  • Insulting the intelligence of the Fed (though, strangely, he might be right that it is too worried about inflation) can only have the opposite effect he wants.
  • Partial government shutdown over the wall fetish and fear that Mattis’ departure from Defense removes adult supervision portend escalating distraction and confusion.
  • Public airing of Trump-related stuff by the Democratically controlled House could make the President mad enough to do something daffy.
In the face of all the uncertainty, we think it vain to make a case for value in equities.

Thursday, June 14, 2018

Is Your Daddy Rich and Your Momma Good Lookin'?


This article first appeared on TalkMarkets.com (http://www.talkmarkets.com/content/economics--politics/is-your-daddy-rich-and-your-momma-good-lookin?post=179062)
Sometimes, gentle reader, we think things will be all right, especially when summer rolls in and fish are jumpin’ and the cotton is high.  Why, just the other day we were tooling down the highway in our 18-year-old Saturn station wagon (she and her V-6 can now vote.  Hurray!) and, miracle of miracles, our i-phone music library played beautifully through the cassette deck thingamajig from what had once been a problematic stereo.
Not so fast, you say; OK, we hear you.  Yes, the “check engine” light was still on. But we had Petula Clark telling us that she knew a place where we could go where the lights are low, and Peter and Gordon were assuring us that nobody they knew loved us more than her.  All with no bass rattle!  What’s more, the potholes we had dodged for several months had been filled by conscientious government pothole fillers. As we always say when each day confounds us with good luck: so we’ve got that going for us.
Which means that one of our pillars for equity underperformance – a trade war (see http://www.talkmarkets.com/content/us-markets/what-rough-beast?post=170281) – has been masterfully parried by that stable genius Donald Trump.  He may not know the American lyrics to “God Save the Queen,” or that red coats, not Canadians, who served under that anthem burned the White House down in 1814, but he’s a shameless son of a gun and Wall Street doesn’t care as long as profits keep growing. Yes, the cotton is high indeed.
What we hadn’t counted on was the co-dependency of the United States of America and the People’s Republic of China.  For all the blustering about trade deficits, the USA loves buying cheap Chinese stuff at Wal-Mart so that Beijing gets the dough to buy USA bonds. Duh!
The S&P 500 is up 3.62% this year and up 13.83% year over year.  We find it interesting, though, that the consumer staples sector -- the manufacturers and distributors of Eggo waffles, Marlboros, diet Coke and the like -- is down 12.5% year over year, while information technology is up 28% year over year.  This tells us that investors believe that we wage slaves will never dig ourselves out, while Facebook, etc., will soldier on and raise rents wherever they invade.
The bull in the China shop is the Federal Open Market Committee. Once it starts choking credit as prices rise (try booking a flight from Dixie to NYC this summer!), the proverbial punch bowl will be snatched away before working stiffs like you and us get a raise.
We love the late sunshine; our tan is progressing nicely.  But in two weeks the star that nourishes us will begin its lazy slide into the horizon and so will stock prices, in our view.  The United States 10-year note is at 2.93%, close enough to our buy target of 3%.  Sell stocks, buy bonds.
Forgive us, dear reader, but we must resort to the New Testament for our outlook:
“No trial has come to you but what is human.  God is faithful and will not let you be tried beyond your strength; but with the trial he will also provide a way out, so that you may be able to bear it.” (1 Corinthians, 10:13).
We can bear it if you can, gentle reader.  We’re pouring another diet Coke, opening another pack of Marlboros and plan on toasting an Eggo waffle in the morning.
Monday, March 26, 2018

What Rough Beast?


This article first appeared on Talk Markets.com (&uid=28607)

One of the more athletic of the school’s security guards bounded into the cafeteria one January day, yelling “pow, pow,” hands holding a phantom firearm.  The remedial class of reluctant readers we were overseeing as a substitute teacher scrambled back to our room as instructed by our principal, himself an overseer of the active shooter drill.
We trailed, necktie flapping, Weejuns slipping on the polished linoleum, claudication stabbing us in the lower left leg.  We made it limping through the door, mercifully held open by our charges, literate in empathy if not the printed word.  Maybe they couldn’t, and didn’t want to, read, but the high school sophomores and juniors were nice enough guys and gals not to lock the door until their not so beloved Mr. Chips scooted inside.
Our faux escape accomplished, we returned to the lost cause of cultivating a taste for odes evoking beauty and truth versus Instagram and wondered “what rough beast, its hour come at last,” had been born among us.
Indulgent readers will forgive us for mixing our Keats and Yeats, but we wonder if they’ll forgive lawmakers who refuse to take the common-sense measure of outlawing firearms that discharge a whole lot of bullets real fast (buy Dick’s Sporting Goods). It was done once from 1994-2004 and the Republic survived.  This is so truly a no-brainer that it strains one’s sufferance of the gun-centric crowd that worries its “rahts” (as non-Southerners mock our accent) will be compromised.
Enough preaching.  In the meantime, the “four ‘easter” battering the Eastern Seaboard this spring is an apt metaphor for the four things that spell doom for equity investors in 2018.
  • Withdrawal of monetary stimulus.  This is the biggest.  The Federal Open Market Committee, under the new regime of Fed Chairman Jerome Powell, hiked, as expected, the Fed Funds rate 25 basis points at its meeting yesterday.  If inflation is the result of too much money chasing too few goods, the bull market has been fueled by too much money chasing too few assets.  It’s ending.
  • Overvaluation.  The market is priced at 143% of gross domestic product.  Experience says returns will be subpar until this ratio reverts to the mean.
  • Trade wars.  President Donald Trump appears bound and determined to impose tariffs in an effort to erase the U.S. trade deficit.  As a wiser head than us (wish we could recall who it was) has said something to the effect: A trade deficit is not a bad thing or a good thing, it’s just a thing.
  • Trump himself.  Whether it’s Mueller or Stormy who rocks his world, unpretty things await.  In a way, though, Republicans might be glad to be rid of him and work with reliable conservative VP Pence, we think.
In any event, gentle reader, we think equities are dead money or worse for a while.  The likeliest bull market to come, despite Fed tightening, is bonds, we believe.  We know that some heavy-hitting interest rate gurus believe bond prices are headed downward.  But we think an inverted yield curve looms as the Fed squeezes and investors flee to safer assets.  If the 10-year note yield hits 3% (it’s currently about 2.85%), it’s a screaming buy, we think.

Monday, February 5, 2018

The Truth About Time

If timing is everything, how come it ain’t in ye olde financial markets, as a myriad of experts will tell you? 

Here’s what they really mean: Of course timing is everything, even in investment decisions, but we don’t want to be wrong, so we advise not timing the market even as we tell you to buy or sell.  Even more infuriating is the fellow who’ll tell you he was right but his timing was off!

Well, gentle reader, we’re that second fellow.  Please click on TalkMarkets for more)

Thursday, January 25, 2018

A Stable Genius Guide to 2018

The hour is getting late, as Bob Dylan told us while businessmen drank his wine and plowmen dug his earth, but never too late, dear reader, for our annual outlook all along the watchtower.

Our back-of-the envelope estimate for real fourth-quarter gross domestic product growth is an annual rate of 3.3%, higher than the consensus of 3.0%.  The Atlanta Fed’s GDP Now calculation pegs growth at 3.4%, citing better-than-expected December retail sales.  In any event, it’s safe to say growth was between 3-4%, sustaining the 3%-plus rates of the second and third quarters.  The rest of the world is doing well, too.  But just as the U.S. was the engine that pulled the global economy into expansion, it’ll be the millstone that drags it down, too, we think.

We must, however, note first of all that, being stable geniuses, we reserve the right to alternative facts, should we prove wrong.

  • Trumpism will fade like an old man sitting on a sofa contemplating raking the leaves; it’s simply too much to ask and still think about stuff like porn star hookups and infrastructure.

  • Recession will loom as the yield curve flattens and inverts.  The Fed will tighten too much and investors will flee to T-notes as scary stuff happens

  • What scary stuff?  We’re geniuses, not soothsayers, but the potential list includes North Korea, terrorism, Donald Trump off the rails and the New England Patriots supplying their own refs for the Super Bow.

  • With U.S. stock market capitalization already at 150% of GDP, a sell-off is inevitable after the Fed puts the screws to the economy and, well, screws it up.  Wait for the crash, then buy Amazon.

  • We famously predicted a Trump victory (see here), and now we predict Democrats will retake control of one of the houses of Congress, insuring and even less perfect union and all the blessings of deadlock.

  • Tiger Woods will play creditably in his comeback but fail to win a single tournament.  The field is too good.  Sell Nike (and Under Armour; Jordan Spieth won’t win either).

  • Despite Oklahoma’s freshman sensation Trae Young, Kansas will win yet another conference title and make it to a final four that includes Duke, Villanova and a commuter school whose players are inspiring inner-city stories that Jim Nance will pretend to care about.

  • The new Yankee manager Aaron Boone will start a trend by going to his mighty bullpen by the third inning.  Since more pitchers will be needed on rosters, this will spark a desperate search for pitcher/hitters like the Japanese fellow the Angels hired.  This will expand the definition of “Ruthian.”

  • The Eastern Seaboard will gain population at the expense of catastrophe prone California, driving already steep housing costs beyond the means of all indigenous tribes of teachers, firemen and police.  Shithole countries will be designated to provide replacements.  Indeed, lawyers specializing in procuring shithole status for immigrants will flood late night TV abroad.

  • Despite signs of the Apocalypse everywhere, Jesus may not return.  We won’t be disappointed, though.  Our preference, as it is every new Anno Domini, is for many more circuits around His creation before He calls in His note.  Happiest and healthiest of new years to all!